Hidden Costs of Paying in Your Home Currency Abroad
As participants in Amazon Associates and other programs, we earn from qualifying purchases. This comes at no additional cost to you. For more details, see our Affiliate Disclosure.
Every time a merchant abroad offers to charge your card in your home currency, you’re likely paying a hidden premium you never agreed to.
Understanding Dynamic Currency Conversion and Its Mechanics
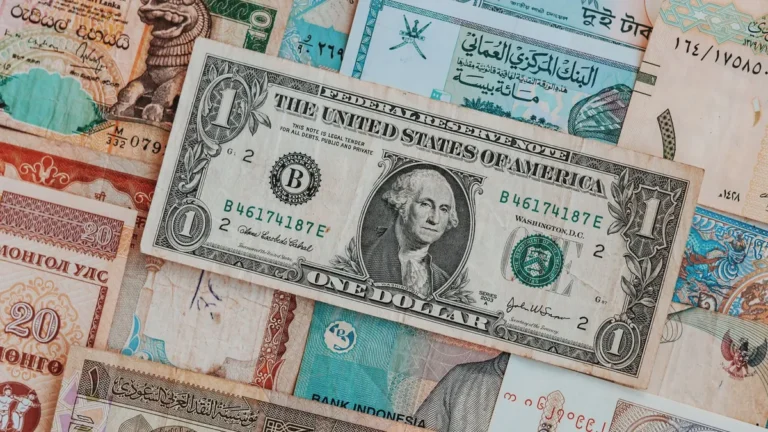
Dynamic currency conversion (DCC) lets merchants convert your transaction into your home currency at the point of sale. The problem is that real money is converted into a virtual currency that obscures the true cost, making it easy to overspend without realizing it.
This is a well-documented deceptive design pattern that exploits the user’s unfamiliarity with local currency values. You feel comfortable seeing dollars or pounds, but the exchange rate applied is rarely in your favor.
How DCC Exchange Rates and Markup Fees Impact Your Transactions
DCC markups typically range from 3% to 12% above the interbank exchange rate, according to Visa’s DCC overview. That means on a €500 hotel bill, you could lose up to €60 purely to conversion fees.
To put that in perspective, small consistent charges add up fast — much like how a $1 price increase across thousands of veterinary transactions can generate $20,000 in annual revenue. Every dollar of unnecessary DCC fees compounds across your entire trip.
Merchant Disclosure Requirements and Your Right to Opt Out
Merchants are legally required to disclose DCC terms before you agree to pay. If they fail to do so, you have grounds to dispute the charge under the Fair Credit Billing Act (FCBA) of 1974, which caps your liability at $50 and grants the right to contest unauthorized or misleading billing — learn more about chargeback laws and your consumer rights.
Always say “pay in local currency” when prompted at a terminal or ATM. That single choice eliminates DCC entirely.
Comparing DCC Costs Against Standard Currency Conversion Methods
Your card network’s standard conversion rate is almost always cheaper than DCC. If you want to minimize foreign transaction fees while traveling, always decline DCC and use a card with no foreign transaction fees.
Travelers heading to specific destinations should also research local payment norms — for example, understanding cash vs. card options in Australia helps you plan which payment method avoids unnecessary conversion costs altogether.