Why Travel Insurance Claims Get Denied: Key Clauses
As participants in Amazon Associates and other programs, we earn from qualifying purchases. This comes at no additional cost to you. For more details, see our Affiliate Disclosure.
Travel insurance claims denied are more common than most travelers expect — and the reasons are almost always buried in policy fine print.
Common Denial Triggers: Pre-Existing Conditions and Policy Exclusions
When a claim is rejected, you receive a denial letter outlining the specific reason. The most frequent causes include pre-existing conditions, treatments during the waiting period, excluded conditions, lapsed coverage due to missed premiums, and incomplete records.
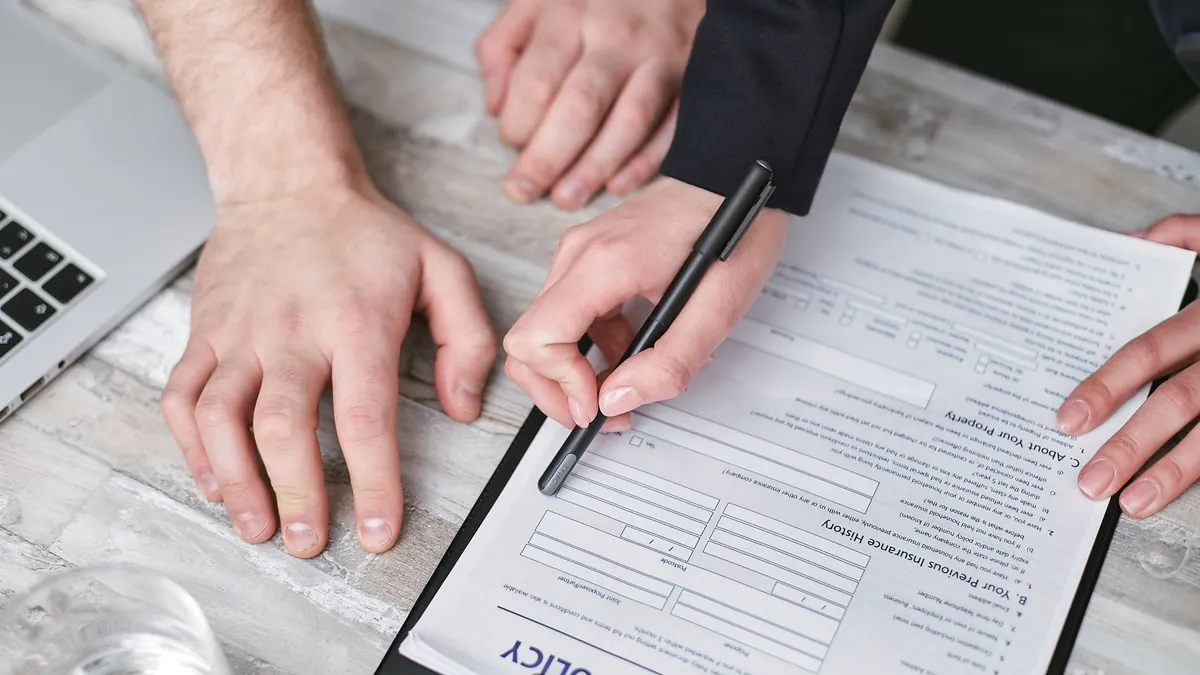
Insurers treat pre-existing conditions strictly — any diagnosis or symptom documented before your policy’s effective date can void a related claim entirely. Always disclose medical history accurately when purchasing coverage.
Policy exclusions are equally dangerous. Adventure activities, pandemics, and civil unrest are routinely excluded unless you purchase specific add-on riders.
Critical Documentation Requirements and Proof Standards for Claim Approval
Missing or incomplete documentation is one of the top reasons travel insurance claims get denied. Insurers require receipts, medical reports, official cancellation notices, and police reports where applicable.
If your trip is disrupted by an airline issue, keep every piece of written communication from the carrier. This documentation directly supports your claim and prevents disputes — similar to how you’d handle airline ticket disputes step by step.
Policy Coverage Limitations and What Travel Insurance Actually Protects
Travel insurance does not cover everything. Standard policies typically protect trip cancellation, medical emergencies, baggage loss, and travel delays — within defined limits.
Coverage caps mean a $10,000 medical bill may only receive a $5,000 payout. According to InsureMyTrip’s regulatory overview, travel insurance is overseen by state insurance regulators who enforce consumer protection laws — not a single federal agency.
If you’re traveling internationally, check whether active travel advisories affect your destination, as government-issued warnings can directly impact claim eligibility.
Filing Deadlines and Appeal Processes for Rejected Claims
Most insurers require claims to be filed within 20 to 90 days of the incident. Missing this window almost guarantees a denial regardless of eligibility.
If denied, you have the right to appeal. Submit a written appeal with additional documentation, and escalate to your state insurance regulator if the insurer remains unresponsive. Acting fast and staying organized is your strongest defense.