Hotel Pre-Authorization Over Credit Limit: What Happens
As participants in Amazon Associates and other programs, we earn from qualifying purchases. This comes at no additional cost to you. For more details, see our Affiliate Disclosure.
Checking into a hotel should feel like the beginning of something exciting — not a financial ambush waiting at the front desk. Most travelers assume that as long as their card covers the room rate, the check-in process will be seamless and uneventful. What they rarely anticipate is a hold that quietly swallows hundreds of dollars in available credit before a single night is even spent.
The mechanics behind a hotel pre-authorization credit card hold are widely misunderstood, and that gap in knowledge costs travelers real money and real stress. A hotel’s hold can easily exceed a guest’s remaining credit limit, triggering declined transactions, frozen accounts, and a scramble for answers that no one at the front desk is fully equipped to resolve. Understanding exactly what happens in that moment — and why — changes everything about how you travel.
Hotel Pre-Authorization Holds Are a Temporary Freeze, Not a Real Charge
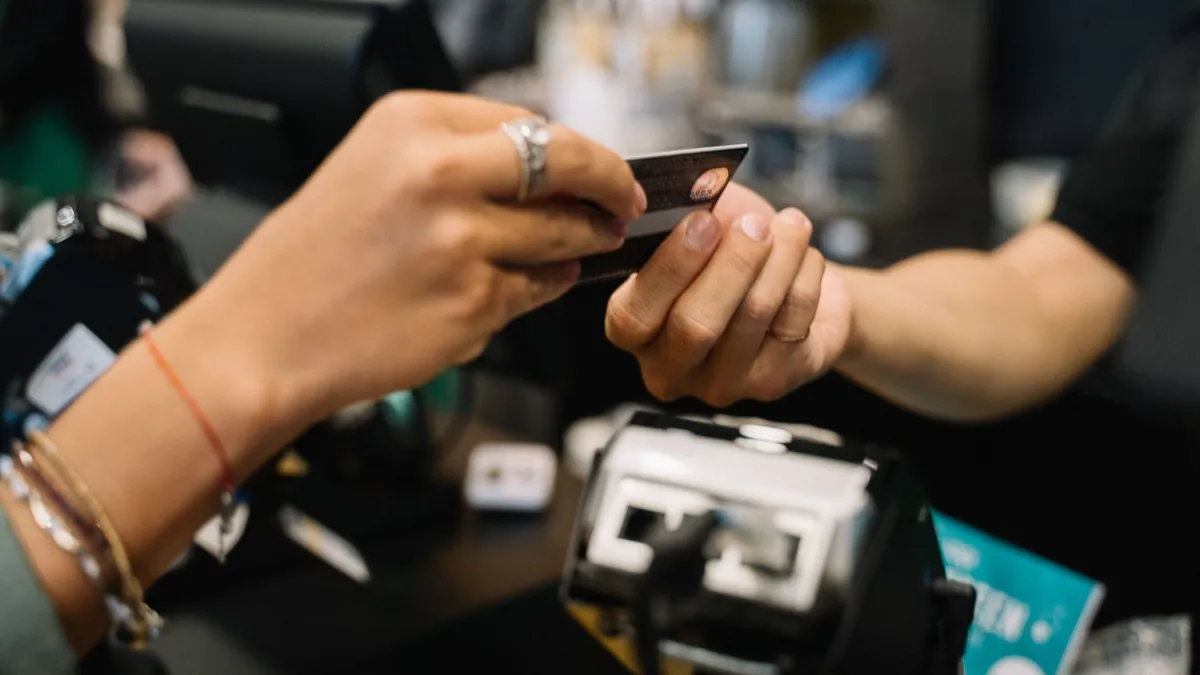
When a hotel places a pre-authorization on your card, it is requesting that your bank ring-fence a specific amount of your available credit — typically covering the full stay plus an incidental buffer ranging from 50 to 200 dollars per night. This is not an actual charge; no money leaves your account, but that reserved amount becomes completely inaccessible. The deeper explainer on hotel credit card hold mechanics reveals just how aggressively some properties apply these buffers, often without transparent disclosure at booking.
If your available credit sits below the hotel’s total authorization request, your bank may partially approve, decline outright, or flag the card — each outcome creating a different headache. According to PayJunction, itemizing all charges and documenting pre-authorizations with clear client agreement is the industry’s strongest defense against disputes and costly write-offs. The problem is that most guests never receive that documentation proactively.
Reversal Timelines and the Real Cost of Going Over Your Limit
Once a pre-authorization exceeds your available credit, the reversal process — even after checkout — can take anywhere from 3 to 10 business days depending on your card issuer and the hotel’s payment processor. During that window, your credit remains frozen, meaning any travel purchases you planned to make — flights, meals, car rentals — may be declined. PCI-DSS compliance standards require hotels to handle stored card data securely, but they impose no obligation on how quickly a property must release an authorization hold.
The smartest prevention strategy is arriving with a card that carries at least 150% of your anticipated total bill in available credit, specifically reserved for the stay. Booking during off-peak windows, as explored in the context of September vacation rental deals, can also reduce the nightly incidental buffer hotels apply during high-demand periods. Additionally, research from Resort Forward confirms that when digital booking experiences align with actual guest psychology, properties see reduced abandonment and stronger trust — meaning transparent hold disclosures at checkout pages genuinely improve conversion and guest confidence.
A hotel pre-authorization credit card situation that exceeds your limit is disruptive, but it is entirely survivable with the right preparation and the right card in your wallet. Knowing the reversal timeline, documenting every hold amount, and choosing properties that disclose their policies upfront transforms a potential financial ambush into a manageable, expected part of travel. Have you ever had a hotel hold freeze your card at the worst possible moment — share your experience in the comments below.